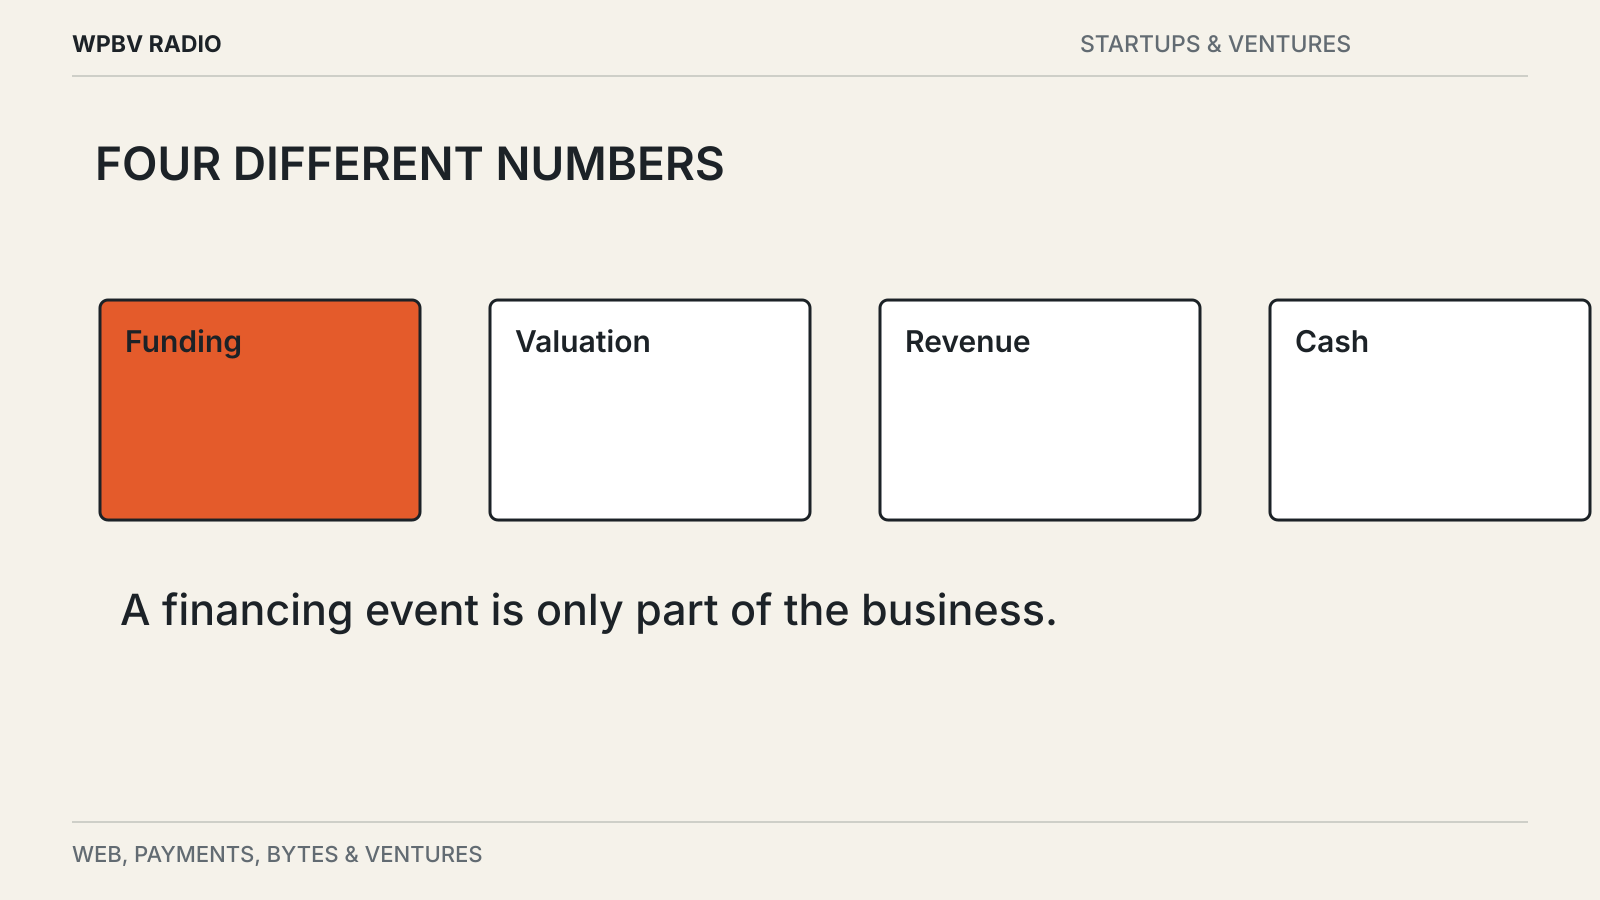
A startup announces a large funding round at a larger valuation. The figures make a clear headline. They do not tell you whether the product is profitable, how much money reached the company or what rights the investors received.
A funding announcement is evidence of a financing event. To understand the business, separate the transaction from the operating results.
The headline contains different kinds of numbers
Money raised is not revenue. Revenue comes from providing goods or services to customers; investment finances the company in exchange for rights or obligations.
A valuation is not the amount of cash in the bank. It is a value associated with the financing or transaction, subject to its structure. If the announcement does not distinguish pre-money and post-money valuation, avoid performing ownership calculations from the headline alone.
Also check whether a round includes debt or secondary share sales. Debt introduces repayment terms. A secondary sale pays an existing shareholder rather than necessarily adding money to the company’s operating account. Some announcements combine several components.
The instrument matters
Not every early investment immediately sets a price for ordinary shares. A financing may use an agreement that converts into equity under specified conditions.
Y Combinator’s SAFE documentation explains one widely used structure and its variants. A valuation cap in such an agreement should not automatically be described as a completed priced-round valuation. The document’s conversion mechanics matter.
For a news reader, the practical point is to preserve the company’s actual terminology. If an announcement says “financing” without a breakdown, report that uncertainty rather than silently relabeling the whole amount as equity.
Ask what the operating metric measures
A company may report revenue, annual recurring revenue, bookings, payment volume or gross merchandise value. These numbers describe different things.
Payment volume can be large while the business retains only a small fee. Bookings may represent contracts whose revenue will be recognized later. Annual recurring revenue is a run-rate measure with a definition that needs to be understood, especially when usage changes sharply.
Compare like with like, and keep the time period attached. A percentage growth claim is hard to assess without the starting base. “Doubled” means something different for a new product with ten customers than for an established service with thousands.
More capital creates options and expectations
Funding can pay for hiring, infrastructure, product development or expansion. It can also replenish cash consumed by an existing business.
The announcement’s use-of-proceeds paragraph describes intentions. It does not establish that the hiring will succeed or the new product will find customers. Watch for later evidence: released features, active usage, retention and a clearer account of costs.
The investor list can help explain the company’s network and financing support. It is not independent proof that the product works or that the investment will produce a return.
Read the next announcement against this one
Save the original date, amount, stated valuation and named metrics. Later, compare changes using the same definitions. A larger valuation with little operating disclosure still leaves operating questions unanswered.
For software businesses, customer economics often reveal more than a celebratory funding figure. Our guide to AI startup revenue per user shows how the cost of serving a customer changes the picture.
This approach is useful even if you never invest. Customers choosing a long-term software supplier care about whether the company can support the product, honor commitments and maintain a workable business model.