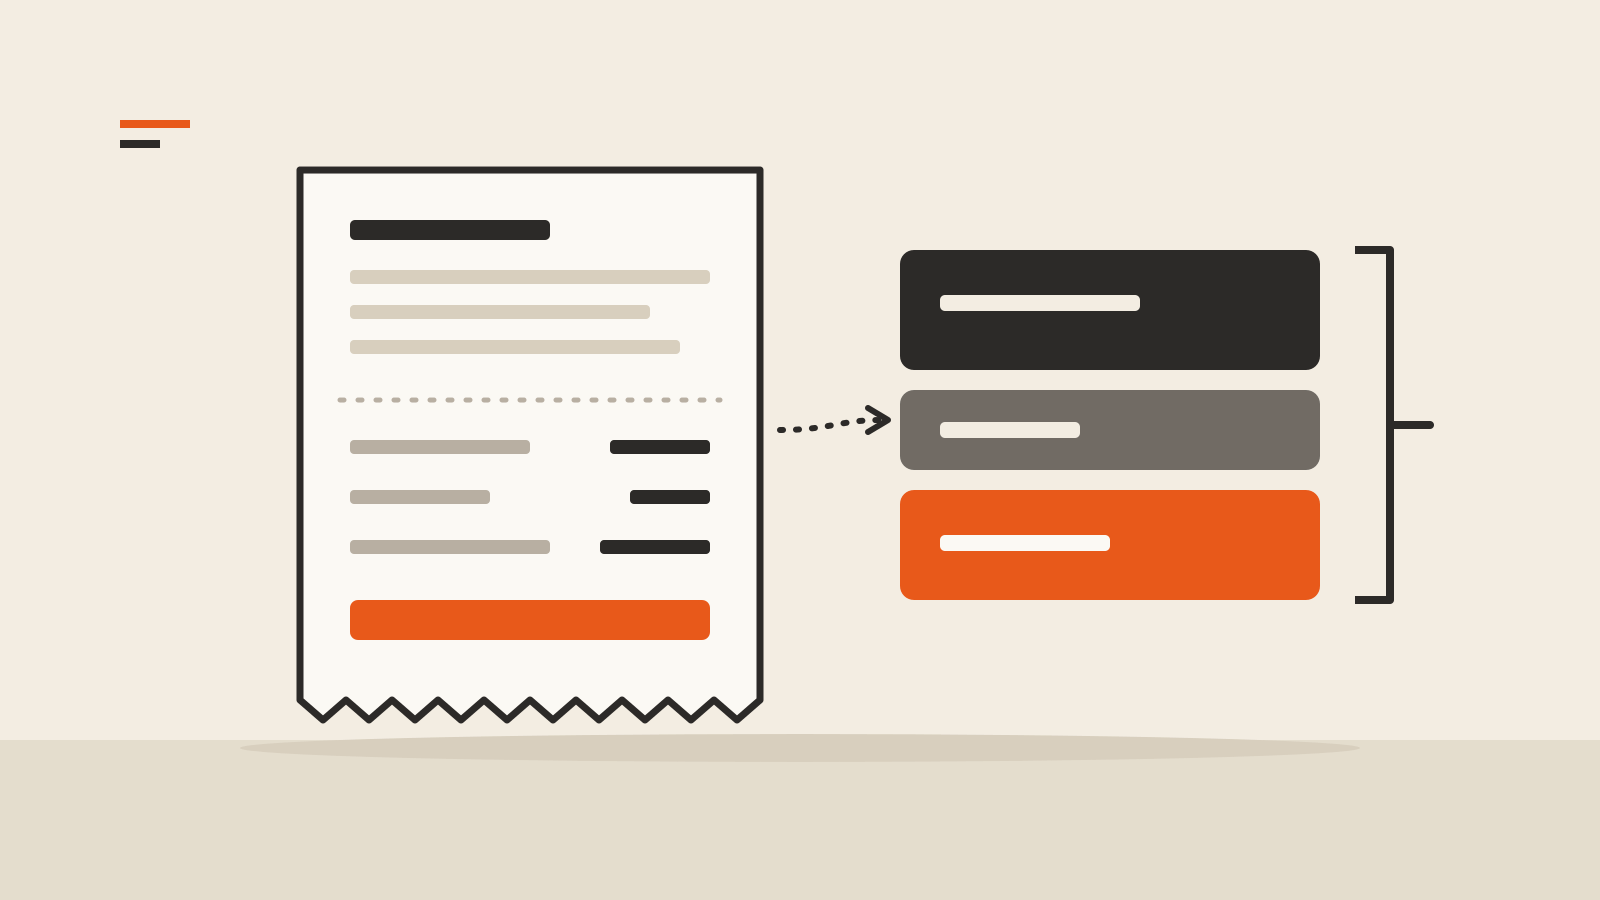
A shop owner in Lisbon compares two offers from card acquirers. One quotes a single percentage, the other lists interchange, scheme fees and a margin. A supplier in India mentions “MDR,” and a US processor’s contract talks about the “discount rate.” The interchange fee vs MDR question sounds like jargon, but the difference decides which number you can negotiate and which one you cannot.
The short answer: the merchant discount rate (MDR) is the total charge a merchant pays its acquirer to accept a card payment. The interchange fee is one part of that total, the part that ends up with the bank that issued the customer’s card.
The MDR is the whole charge
The Reserve Bank of India gives one of the clearest official definitions in its 2022 discussion paper on charges in payment systems. It describes the MDR as “the charge recovered by the acquirer from the final recipient of money (i.e., merchant),” levied “as a discount to the transaction amount and usually recovered during settlement.” That is where the name comes from: the merchant receives the sale amount minus a discount.
European law uses a different name for the same idea. Regulation (EU) 2015/751, the EU Interchange Fee Regulation, defines a “merchant service charge” as “a fee paid by the payee to the acquirer in relation to card-based payment transactions.” Merchant service charge, MSC, discount rate and MDR all point at the same thing: the price of card acceptance as the merchant sees it.
On a flat-rate plan, the MDR is simply the advertised rate. On an interchange-plus plan, the MDR is the sum of the lines on the statement. Our guide to interchange-plus vs flat rate covers how the two pricing models present it.
Interchange is one slice inside it
The same EU regulation defines the interchange fee as “a fee paid for each transaction directly or indirectly (i.e. through a third party) between the issuer and the acquirer involved in a card-based payment transaction.” The merchant never pays interchange to the card issuer directly. The acquirer pays it, then recovers it from the merchant as part of the MDR.
The RBI paper describes the split the same way: MDR collected by acquirers compensates the card issuer, the acquirer and the card network, with the issuer-network-acquirer division “based on the rules prescribed” by the network. In a typical card payment, then, the MDR covers three things:
- Interchange, paid to the issuing bank. The card network sets the rates, and regulators cap them in some markets.
- Scheme fees, paid to the card network, such as Visa or Mastercard, for using its system.
- The acquirer’s margin, which covers the acquirer’s or payment provider’s costs and profit.
Our explainer on the interchange fee walks through who receives each share.
Why the difference matters
Only one of the three slices is fully up for negotiation with your provider. Interchange follows the network’s published tables and any legal cap. Scheme fees are set by the network. The acquirer’s margin is the provider’s own price. When a provider quotes a single MDR, you cannot see how much of it is margin.
The EU addressed this directly. Under Article 9 of the regulation, each acquirer must “offer and charge its payee merchant service charges individually specified for different categories and different brands of payment cards with different interchange fee levels,” unless the merchant asks in writing for a blended rate. Acquirers must also put “individually specified information on the amount of the merchant service charges, interchange fees and scheme fees” in their merchant agreements. Article 12 requires the acquirer, after each card payment, to show “the merchant service charge and the amount of the interchange fee” separately, though the merchant can agree to aggregated, at least monthly reporting.
India’s central bank pushed the same way. In a 2016 circular on unbundling of MDR charges, the RBI said bundled fees “levied on merchants irrespective of the type of card used” hindered compliance, and told acquiring banks to unbundle MDR for different categories of cards.
Where regulators cap each part
Caps usually land on interchange, not on the full MDR, and the difference shows up on the statement:
- European Union. The Interchange Fee Regulation caps interchange on consumer debit card transactions at 0.2% and on consumer credit card transactions at 0.3% of the transaction value. It caps interchange, not the MDR, so scheme fees and the acquirer’s margin come on top. Commercial cards are outside the caps, according to Article 1 of the regulation.
- United States. The Federal Reserve’s Regulation II limits debit card interchange for large issuers. Credit card interchange has no federal cap.
- India. Here the rules reach the whole MDR. The RBI paper notes that under section 10A of the Payment and Settlement Systems Act, RuPay debit cards and UPI were notified as payment modes on which no bank or system provider may charge, and that zero charges took effect on January 1, 2020.
So a “0.2% cap” in Europe does not mean a merchant pays 0.2% to accept a debit card. It means the issuer’s slice cannot exceed 0.2%. The full MDR is that slice plus the network’s and the acquirer’s.
How to read your own statement
Take one recent card payment and find three numbers:
- The total fee. Divide it by the sale amount to get your effective MDR for that payment.
- Interchange, if listed. On an interchange-plus or IC++ statement it appears per card category. On a flat-rate plan it usually does not appear at all.
- Everything else. Total fee minus interchange is what goes to the network and your provider. If scheme fees are listed separately, what remains is your provider’s margin, the one number you can negotiate.
Repeat for a debit card, a credit card and a foreign card, because interchange differs by card type and region. To compare the standard published rates of major providers for a single payment, use our payment fee calculator.